
Prepare with CIMA F1 exam torrent, pass for sure

Last Updated: Sep 30, 2026
No. of Questions: 247 Questions & Answers with Testing Engine
Download Limit: Unlimited
Latest and high-quality F1 vce test simulator pass for sure
Test4Sure F1questions and answers provide you test preparation information with everything you need. Study with our F1 test practice torrent, your professional skills will be enhanced and your knowledge will be expanded. What's more, F1 practice pdf will ensure you a define success in our F1 actual test.
100% Money Back Guarantee
Test4Sure has an unprecedented 99.6% first time pass rate among our customers.  We're so confident of our products that we provide no hassle product exchange.
- Best exam practice material
- Three formats are optional
- 10 years of excellence
- 365 Days Free Updates
- Learn anywhere, anytime
- 100% Safe shopping experience
- Instant Download: Our system will send you the products you purchase in mailbox in a minute after payment. (If not received within 12 hours, please contact us. Note: don't forget to check your spam.)
CIMA F1 Practice Q&A's

- Printable F1 PDF Format
- Prepared by F1 Experts
- Instant Access to Download
- Study Anywhere, Anytime
- 365 Days Free Updates
- Free F1 PDF Demo Available
- Download Q&A's Demo
CIMA F1 Online Engine

- Online Tool, Convenient, easy to study.
- Instant Online Access
- Supports All Web Browsers
- Practice Online Anytime
- Test History and Performance Review
- Supports Windows / Mac / Android / iOS, etc.
- Try Online Engine Demo
CIMA F1 Self Test Engine

- Installable Software Application
- Simulates Real Exam Environment
- Builds F1 Exam Confidence
- Supports MS Operating System
- Two Modes For Practice
- Practice Offline Anytime
- Software Screenshots
One-year update freely
According to aims and principle of our company, we have been trying to make every customer feel satisfied at our services and develop our F1 demo questions to suit with the requirements of syllabus of F1 practice exam. Our experts have analyzed exam outline and take notice of every little changes to update our materials. So once you purchase our products, we will send the new updates to your mailbox lasting for one year for free. Please remember to check mailbox and practice them regularly, which is also of great use to your exam connected with CIMA Certification F1 study vce, and this kind behavior is totally free as our little gift for you.
Considerable services for clients
Our employees fulfill their duty and responsibility to help customers solve every issue or questions you may have during the usage process. If you are confused about anything related to our F1 : Financial Reporting training pdf just post questions and connect with them. They are waiting to offer help 24/7 with patience and hearty attitude. Generally speaking, they will solve them as soon as possible and help you get rid of anxiety. Apart from what has been mentioned above, our company aims to relieve clients of difficulties and help you focus on reviewing efficiently, that is the reason why we have established great reputations and maintained harmonious relationships with clients and have regular customers around the world.
Professional expert groups
Today's consumers are discerning and demand quality products with real usage, but our F1 products still can stand the test of market and qualify ourselves diligently by hiring a bunch of first-rank professional experts with experience of these F1 practice tests fully. These F1 exam pass sure are the newest information required by the certificates community and our experts never stop adding useful changes into them. So we offer the benefits to customers that once you bought our CIMA Certification F1 practice materials and we send updates for one year entirely freely. They are all great materials from painstaking effort of experts, so can be trusted with full heart.
In today's society, we all know the importance of knowledge to your career and lifestyle, so the F1 practice exam is desirable to candidates who are trying to pass the practice exam and get the certificates. Because one useful certificate may cause unexceptionable influence to your future and our products attract millions of clients from all over the world eager to possess them sincerely. To help you get better acquaintance with our CIMA F1 test engine, we would like to provide some succinct introduction for your reference. Please follow us and you will not be regretful for it.
Free demo for your reference
Many customers are unfamiliar about the content of our products for their first purchase, and as you know we cannot touch the digital products from the internet, maybe you will be a little hesitant to us, while the worries have been solved absolutely as we have offered some representative demos for you to take an experimental look. You can download them and look through thoroughly before placing your order of our F1 updated study material. Under each kind of F1 practice test we offer one demo for you, which includes a part of real content of the F1 study vce and serve as a good help for you get acquainted with our products quickly.
CIMA F1 Exam Syllabus Topics:
| Section | Weight | Objectives |
|---|---|---|
| Managing Cash and Working Capital | 25% | - Management of receivables, inventory and payables - Working capital cycle and objectives - Cash management and forecasting - Short-term financing options |
| Financial Statements | 45% | - Interpretation and analysis of financial statements - Preparation of single entity financial statements
|
| Principles of Taxation | 20% | - Deferred tax concepts - Current tax calculation - Tax system and types of taxes - Indirect taxes overview |
| The Regulatory Environment of Financial Reporting | 10% | - Conceptual framework and regulatory bodies - IFRS Foundation and IASB structure - Principles vs rules-based regulation - Ethics in financial reporting |
CIMA Financial Reporting Sample Questions:
Country X levies a duty on alcoholic drinks. Where the alcohol content is above 40% by volume the duty levied is $5 per 1 litre bottle.
What type of tax is this duty?
- A. Single-stage sales tax
- B. Direct tax
- C. Ad valorem tax
- D. Specific unit tax
Correct Answer: D 🗳️
An asset has the following values: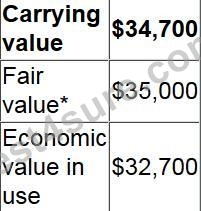
If the asset was sold for its fair value, selling costs of $1,500 would be incurred.
Which of the following is the value of the impairment loss to be recognised for this asset in accordance with IAS 36 Impairment of Assets?
- A. $300
- B. $2,000
- C. $1,200
- D. $0
Correct Answer: C 🗳️
BCD owns an item of plant which cost $20,000 and at the time of purchase was assessed to have a useful economic life of 8 years and a residual value of $2,000.
The carrying amount of the plant at 1 January 20X8 is $11,000. On that date BCD's directors estimate that the plant's remaining useful life is now 6 years.
The residual value remains unchanged at $2,000.
What is the depreciation charge for this plant for the year ended 31 December 20X8?
Give your answer to the nearest $.
Correct Answer:
$1,688
An entity's inventory days are 45 days.
An entity ceased to manufacture a product in 20X4. Raw materials used solely in the manufacture of that product are still held in inventory at 31 December 20X4.
Place the appropriate response below to show how inventory days will be affected if this raw material inventory is written off as obsolete.
Correct Answer:


The statement of profit or loss for PQ, ST and AB for the year ended 31 December 20X0 are shown below:
1. PQ acquired 80% of its subsidiary, ST, on 1 January 20X0 and 40% of its associate, AB, on 1 September 20X0.
2. Since acquistion PQ has sold goods to ST and AB for $20,000 and $30,000 respectively. At the year end both ST and AB have 50% of these goods remaining in inventory. PQ uses a mark-up of 20% on all of its sales.
3. Since acquisition the goodwill in respect of ST has been impaired by $8,000 and the investment in AB has been impaired by $2,000.
4. PQ uses the fair value method for non-controlling interest at acquisition.
Calculate the profit attributable to the non-controlling interests disclosed in PQ's consolidated statement of profit or loss for the year ended 31 December 20X0.
Give your answer to the nearest whole $.
Correct Answer:
$8000
 Brian
Darcy
Fitzgerald
Hugo
Lawrence
Morton
Test4Sure is the world's largest certification preparation company with 99.6% Pass Rate History from 59470+ Satisfied Customers in 148 Countries.

Over 59470+ Satisfied Customers


